
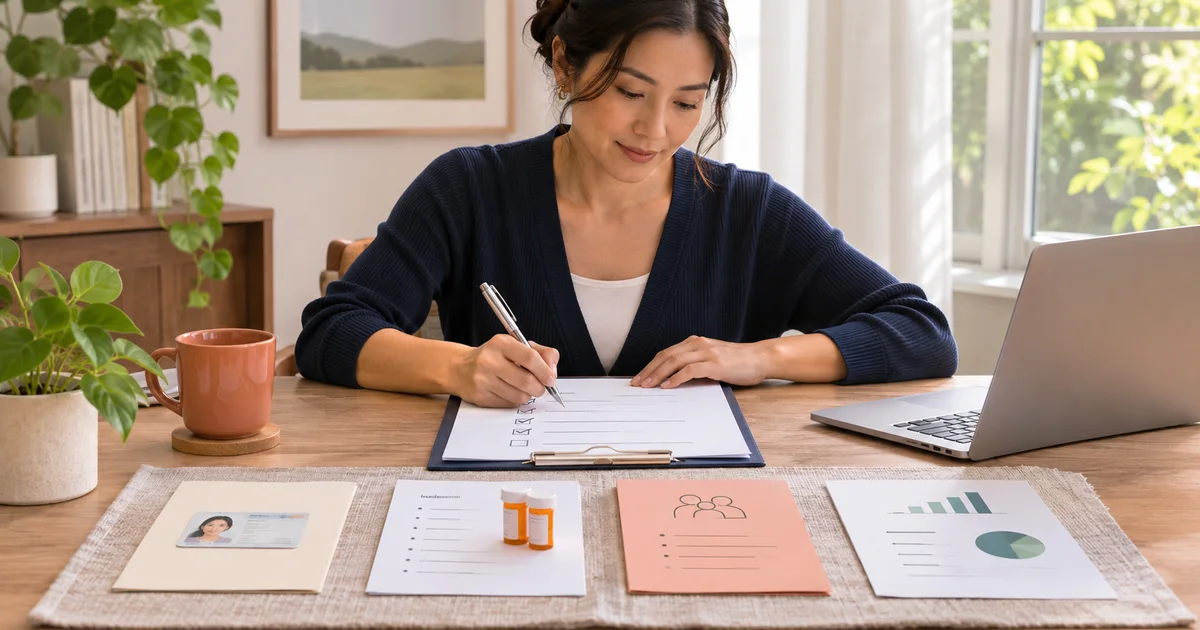
Prepare before requesting quotes
Estimate the death benefit and coverage period before discussing products. Gather current policies, workplace benefits, debts, income needs and available savings. This keeps a quote from becoming the plan and makes competing offers easier to compare. Before submitting an application, review what can happen during a life insurance medical exam and keep a copy of every answer.
Prepare a factual health and lifestyle timeline. Applications can ask about diagnoses, prescriptions, treatment, tobacco or nicotine use, driving, travel, occupation and hazardous activities. Exact questions vary, so read each one rather than relying on a verbal summary.
Before moving on
- Write down the coverage amount and intended duration.
- List doctors, prescriptions and recent treatment dates.
- Gather identification and beneficiary details.
- Keep existing policy numbers and premium records.
Compare preliminary quotes correctly
Hold the applicant, death benefit, term, riders and payment frequency constant. Confirm whether each price is an estimate for a preferred class or an offer based on completed underwriting. An advertised rate is not the final premium for a specific applicant. Before sending personal information, verify how to choose a life insurance company.
Check insurer identity and licensing through the relevant state insurance department. Financial-strength ratings and complaint information can add context, but no single measure predicts an individual claim outcome.
What this step can look like
One quote shows $42 monthly for a preferred class and another shows $520 annually for a standard class. The prices cannot be compared fairly until both use the same class and payment schedule. Annualizing the first quote gives $504, but the underwriting difference still matters.
Complete underwriting accurately
The insurer may use an interview, medical exam, laboratory results, prescription information, motor-vehicle records and other authorized data. A no-exam process can still use health questions and external data. Read authorizations and ask how inaccurate information can be corrected.
Answer from your own records when possible. Do not omit a diagnosis or medication because someone says it is unimportant. Review the completed application before signing and keep a copy, including amendments made during underwriting.
Before moving on
- Verify every application answer before signing.
- Save consent forms and exam receipts.
- Respond to follow-up questions by the stated deadline.
- Ask for the reason if the final class differs from the quote.
Review delivery and place coverage in force
When the policy arrives, compare the declarations, benefit, premium, riders, exclusions and ownership with the accepted offer. Follow any delivery, amendment and first-payment requirements. Coverage is not necessarily active merely because an application was submitted or approved.
Use the free-look period to read the contract and ask questions. Do not cancel an existing policy until the replacement has been issued, accepted and confirmed in force. Store the policy and application where a trusted person can find them.
Keep an application decision log
Record the coverage need, chosen amount, term, owner, insured person and beneficiaries before the application begins. During underwriting, note each request, the date supplied and any correction made. This log prevents a long process from turning into scattered emails and helps the applicant review the final offer against the original goal.
At delivery, compare the issued premium, benefit, class, riders and effective date with the accepted offer. Read payment instructions and the free look notice. Do not cancel existing insurance until the new policy is active and the replacement decision is complete. Store the policy, application and delivery confirmation together.
Before moving on
- Write the purpose and duration of coverage.
- Track every requested document and correction.
- Compare the issued schedule with the application goal.
- Confirm active coverage before ending an old policy.
What this step can look like
Delivery example: If a rider requested on the application is missing from the issued schedule, ask for an explanation before accepting the policy. Do not assume a sales illustration added it to the contract.
Sources for this process
The process can vary by insurer and state. Use the sources below, written insurer instructions and the issued contract to confirm the required steps. Use the life insurance glossary for plain-English contract definitions.