
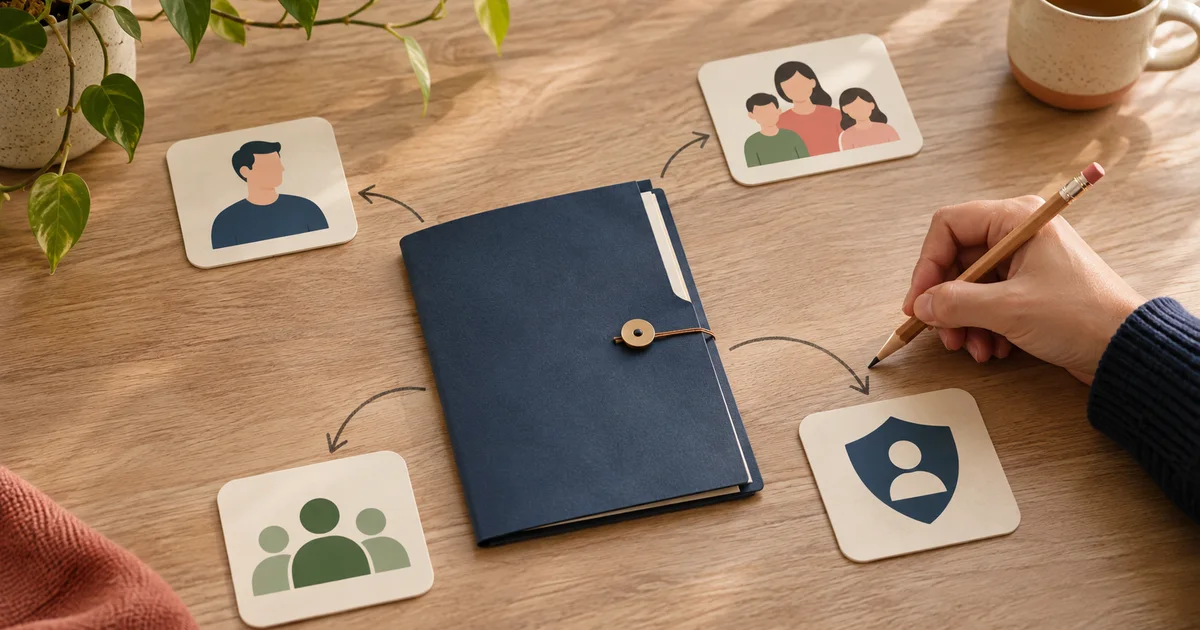
The four roles in a policy
The insured person is the life covered. The owner controls the policy and can usually change beneficiaries. The premium payer supplies the money, and the beneficiary receives the covered death benefit. One person can fill several roles, but they are legally distinct. Once the contract roles are clear, compare term and whole life insurance by duration, guarantees and cost structure.
Before moving on
- Confirm who owns the policy.
- Name both primary and contingent beneficiaries.
- Tell a trusted person where the policy is stored.
What the premium buys
Term insurance buys coverage for a defined period. Permanent policies can remain in force for life if required premiums and policy conditions are met, and they may build cash value. Cash value is not automatically added to the stated death benefit. Contract roles become practical when you also understand how life insurance beneficiaries are chosen.
What this step can look like
Decision example: A parent with 18 years until a child becomes financially independent may start by matching a term length to that 18-year need, then compare available 20-year terms.
What can reduce or prevent payment
A lapsed policy does not provide the intended protection. Material misstatements in an application can also create claim problems. Policy loans may reduce a permanent policy's death benefit. Read the contestability, suicide, exclusions, loan and lapse provisions in the actual contract.
Before moving on
- Answer application questions completely.
- Check premium due dates and grace periods.
- Review annual statements for loans or declining values.
How ownership changes the outcome
The owner can usually change beneficiaries, borrow against available cash value, assign ownership and cancel the contract. Those powers can matter in divorce, business planning, trusts and estates. The insured person does not automatically control a policy owned by someone else.
Before changing ownership, ask about gift, estate, creditor and tax consequences. A general beneficiary update is different from transferring the policy itself. Keep insurer confirmation of any accepted change.
What this step can look like
A parent is insured, a business owns the policy and the spouse is named beneficiary. The parent cannot assume they can change the beneficiary personally. The owner named in the contract controls that right unless another agreement or law changes it.
A policy-delivery checklist
Use the free-look period to compare the issued policy with the application and illustration. Confirm names, ownership, face amount, premium, class, riders, term dates and beneficiary percentages. Check whether any answer was changed during underwriting and whether the applicant approved it.
Before moving on
- Save the full contract and signed application.
- Record the first and recurring due dates.
- Set a backup contact for payment notices.
- Keep the insurer's claims contact with estate records.
Follow the contract from application to claim
A policy does not begin with the first quote. The applicant gives information, the insurer evaluates the risk, and the insurer may issue an offer with a specific premium, rating class and effective date. The owner must accept the offer and satisfy the delivery and payment requirements. Keep the application with the policy because it can become part of the contract.
After issue, the owner should track premiums, beneficiaries, loans, riders and notices. At death, a beneficiary contacts the insurer and supplies the required proof. The insurer then checks that the policy was in force and reviews the claim under the contract. This lifecycle explains why accurate application answers and organized records matter as much as the original death benefit.
Before moving on
- Save the signed application and issued policy together.
- Record the effective date and premium due date.
- Give a trusted person the insurer's contact information.
- Read any notice before a grace period expires.
What this step can look like
Practical check: If the quote says $500,000 but the issued schedule says $400,000, the schedule controls. Resolve the difference before accepting delivery rather than assuming the quote changed the contract.
Questions about how life insurance works
These answers clarify the sequence, documents and decisions involved in the process.
Who controls a life insurance policy?
The policy owner controls the contract and can usually change beneficiaries, assign ownership, borrow against available cash value or cancel coverage. The insured person does not automatically control a policy owned by someone else.
Is cash value added to the stated death benefit?
Not automatically. The contract determines how cash value, loans and the stated death benefit interact. Review the policy provisions instead of adding the displayed cash value to the benefit.
Sources for this process
The process can vary by insurer and state. Use the sources below, written insurer instructions and the issued contract to confirm the required steps. Use the life insurance glossary for plain-English contract definitions.