
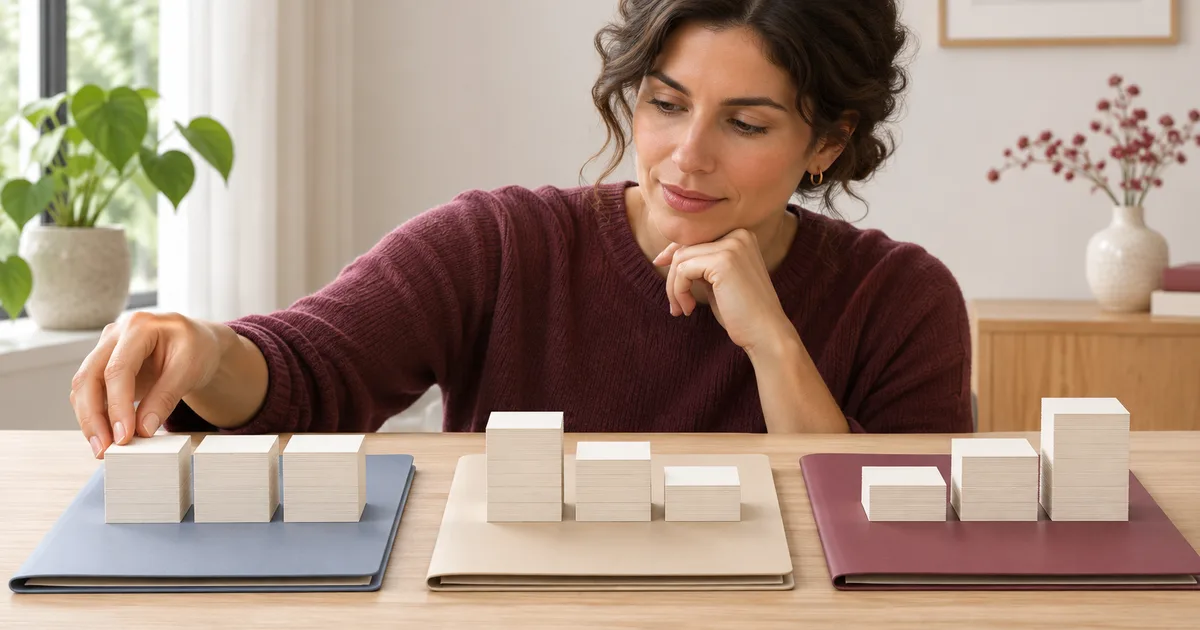
Benefit pattern and premium pattern are separate
Level term usually keeps the death benefit fixed during the selected term. A level-premium guarantee may also keep the premium fixed, but the policy must confirm both. Decreasing term lowers the death benefit over time, often on a schedule designed around a declining debt. Increasing term raises the benefit by a stated amount or option. Use the contract foundation in term life insurance explained before comparing benefit schedules.
Do not infer the premium from the benefit label. A decreasing benefit does not guarantee a decreasing premium. An increasing benefit can require higher premiums or proof of insurability for some increases. Request a year-by-year schedule showing benefit and premium in separate columns.
Points to compare
- Initial and final death benefit
- Benefit change date and formula
- Level-premium guarantee period
- Renewal premiums after the level period
- Age or event limits on increases
Level term supports needs that do not fall neatly
Income replacement, childcare and household transition costs rarely decline on the same schedule as a loan. A level benefit gives the beneficiary flexibility to decide how proceeds are used. It can also create more protection than required in later years if debts and dependency fall faster than expected.
Layering several level term policies with different end dates can approximate a declining need while keeping each contract easy to understand. The tradeoff is more applications, premiums and policy records to maintain.
Decreasing term needs a beneficiary and portability check
Decreasing term can fit a measurable obligation that falls predictably, such as a repayment balance. Some lender-linked mortgage products pay the lender directly or depend on the loan. An individually owned policy may allow the named beneficiary to decide whether paying off the loan is the best use of proceeds.
Check what happens after refinancing, moving or paying the debt early. If coverage does not follow the insured person, a new application may be needed at an older age. Compare the actual benefit schedule with the expected loan balance rather than relying on the product name.
Points to compare
- Who receives the benefit?
- Does coverage continue after refinancing or moving?
- Can the benefit decline faster than the debt?
- Does early repayment end or change coverage?
Increasing term should solve a defined future gap
Increasing term can address inflation, a rising income need or a planned obligation, but contract methods vary. The increase may be automatic, tied to an index, limited by age or available only through a rider. Premiums may rise as the benefit increases.
Compare the maximum future benefit with the maximum future premium. An automatic increase can become unaffordable, while a voluntary increase can be unavailable if the election window is missed. Confirm whether new health evidence is required.
Test three dates before selecting a pattern
Calculate the survivor need at policy issue, the middle of the term and the final covered year. At each date, compare the policy benefit with debts, income support, care work and available assets. This exposes both underinsurance and unnecessary later coverage.
Term design should follow the responsibility rather than a marketing label. When several needs end at different times, a layered plan or adjustable coverage review may provide a closer fit than any single increasing or decreasing schedule.
Sources behind this comparison
The comparison separates policy guarantees, current assumptions and individual facts. Verify the final result against the issued contract and the sources below. Use the life insurance glossary for plain-English contract definitions.